Introduction
The best financial wellness app for your workforce depends on which pressure you are solving. For paycheck timing, an earned wage access platform such as PayActiv. For student loan burden, Peanut Butter. For retirement readiness, Betterment at Work. For everyday budgeting habits, YNAB or Credit Karma. If financial wellbeing is one strand of a wider wellbeing strategy rather than a standalone benefit, a single platform such as Vantage Fit covers financial, physical, mental, and social wellbeing together instead of adding a tenth point solution to your benefits stack.
Key Takeaways
- PwC’s 2026 Employee Financial Wellness Survey found 59% of employees are stressed about their finances, and 49% say their pay is not keeping up with costs.
- In the same survey, 53% of employees had less than $5,000 set aside for emergencies and 30% had less than $1,000, so the gap you are solving is usually liquidity, not literacy.
- The Federal Reserve’s 2025 survey, its most recent, found 37% of adults could not cover a $400 emergency expense with cash or its equivalent.
- Bank of America’s 2026 Workplace Benefits Report found 9 in 10 employers who offer a financial wellness program report a measurable return on it, in employee satisfaction, productivity, and retention.
- Match the tool to the pressure your employees actually report, then pilot with one group and watch weekly active users rather than enrolment before you commit company-wide.
Financial stress does not stay at home. It shows up as distraction, absence, and avoidable turnover, and it is the one major stressor that healthcare and fitness benefits do not touch. The picture is not uniformly bleak: Bank of America recorded employee financial wellbeing at a four-year high in 2026, with credit card debt down 11 points. Both things are true at once, and that is the point. The aggregate is improving while a stressed minority is not, so the useful question is no longer whether to offer something, but which pressure your own workforce is actually under. That is why the ten apps below are assessed on employer fit as much as on features.
What are Financial Wellness Apps?
Financial wellness apps are software solutions that help you manage your finances by keeping track of all your expenses and budgets in one place. These applications offer various tools and features to enhance financial well-being, including debt management, investing, saving, and budgeting. In other words, they enable you to track financial activities, establish and achieve financial goals, and take control of your finances with the help of technology.
For a benefits team, the category splits in two, and the distinction decides what you can actually deploy. Some of these products are consumer apps that an individual downloads and pays for, which means you can recommend them but you cannot buy them for your workforce or see whether anyone uses them. Others are sold to employers, integrate with payroll, and report back in aggregate. Both belong on a shortlist, but only the second kind can be a benefit with a budget line and a measurable outcome.
Key Features of Financial Wellness Apps
Below are some essential features that top financial wellness apps typically offer:
Budgeting Tools: Track income and expenses, categorize spending, and set and monitor budget limits.
Saving Goals: Create specific savings goals, automate savings plans, and track progress.
Investment Management: Track portfolios, receive investment advice and recommendations, and automate investing with robo-advisors.
Debt Management: Track outstanding debts, receive payment reminders, and set debt repayment strategies.
Financial Education: Find articles, videos, tutorials, tips, advice, and calculators that improve financial literacy.
Expense Tracking: Enjoy real-time expense tracking, categorize and analyze spending patterns, and receive alerts for overspending.
Bill Management: Track bills, set payment reminders, view upcoming bills, and automate bill payments.
Credit Monitoring: Track credit scores, receive alerts for changes in your credit report, and get tips for improving your credit score.
Types of Financial Wellness Apps
Financial wellness apps come in various types, each designed to address specific aspects of personal finance. Here are the main categories:
1. Budgeting Apps: Help you track income, expenses, and spending patterns while setting spending caps and providing real-time financial status updates.
Examples: Credit Karma, YNAB
2. Savings Apps: Help you build and manage savings through automated plans, goal-setting tools, and round-up savings.
Examples: Chime, Oportun (formerly Digit)
3. Investment Apps: Make investing accessible with tools for buying and selling stocks, managing portfolios, and using robo-advisors.
Examples: Acorns, Betterment at Work
4. Debt Management Apps: Help you track debts, create payment plans, and stay on top of payments with interest calculators and payoff strategies.
Examples: Qapital, Debt Payoff Planner
5. Expense Tracking Apps: Monitor spending in real time, categorize expenses, analyze spending patterns, and identify unnecessary costs.
Examples: Expensify, Rocket Money (formerly Truebill)
6. Credit Monitoring Apps: Track credit scores and changes in credit reports while offering alerts, tips, and identity theft support.
Examples: Credit Karma, Experian
7. Bill Management Apps: Help you track bills, due dates, and payments with reminders and consolidated views of upcoming payments.
Examples: Rocket Money, Finovera
8. Comprehensive Financial Management Apps: Provide a single suite of financial tools that includes budgeting, saving, investing, debt management, and more.
Examples: Personal Capital, Albert
Trends in Financial Wellness Management
As financial wellness continues to evolve, here are some key trends shaping the future of financial wellness management:
Financial wellness apps are leveraging AI and machine learning for predictive analytics. These tools can foresee changes in income, expenses, or financial risk and offer proactive suggestions to help users adjust their financial plans.
Gamification and rewards are being used to improve engagement and encourage better money habits. Users may receive incentives or badges for hitting savings milestones or staying on budget.
Collaborative features for families and couples are becoming more common, helping users coordinate money management strategies, share information, and set joint goals.
Integration with virtual assistants and voice interfaces is expanding, allowing users to check balances, review transactions, or trigger recurring actions through voice commands.
Companies that integrate these innovative features into their financial wellness programs will likely see increased user engagement, improved financial outcomes, and enhanced overall financial health for their employees or customers.
How to Choose the Best Financial Wellness App?
An individual picks one of these on feel. A benefits team has to answer six questions before signing, and the vendor who cannot answer them clearly is the wrong vendor:
Payroll and HRIS integration: Does it connect to your payroll and HR system, or does someone maintain a spreadsheet of eligibility every month? Earned wage access and loan repayment are impossible to run well without it, and manual eligibility is where these programs quietly die.
Aggregate-only reporting: You need proof of usage without seeing anyone's balances. Ask exactly what the employer dashboard exposes, get it in writing, and repeat it in the launch comms. Employees who suspect their employer can see their accounts will not connect them.
Coverage across your whole workforce: Check eligibility for hourly and shift workers, part-timers, contractors, and any country outside the vendor's home market. Several products in this category are built for salaried domestic staff and silently exclude the people under the most financial pressure.
Security review readiness: Encryption, multi-factor authentication, and a current SOC 2 report or equivalent. These tools link to bank accounts, cards, and payroll, so your security and legal teams will review this whether or not you plan for it. Ask for the documentation up front rather than three weeks before launch.
Adoption support: Who writes the launch communications, who staffs enrolment questions, and what does the vendor commit to on activation? A licence with no rollout support reliably produces low single-digit usage.
Pricing model, not just price: Per-employee-per-month rises with the adoption you want; a flat annual fee does not. Model both against realistic take-up, and confirm whether the quote covers every employee or only enrolled ones.
What Makes a Financial Wellness App Useful in Real Life?
A financial wellness app is only valuable if it helps users make better decisions consistently, not just if it offers a long feature list. Many apps promise budgeting, savings, investing, and tracking in one dashboard, but the real differentiator is whether the user can understand the information quickly and act on it without confusion. The strongest products simplify financial data into actions that feel manageable, such as setting a weekly budget, identifying recurring expenses, increasing savings automatically, or adjusting debt repayment habits.
Ease of use is critical because financial stress often gets worse when people feel overwhelmed by complexity. If an app is cluttered, hard to navigate, or built around financial jargon, adoption usually drops. The better platforms balance depth with clarity. They help users understand where money is going, what habits need attention, and what steps can improve financial stability over time. A clean interface, helpful alerts, simple goal creation, and accurate account syncing all contribute to better day-to-day engagement.
Another major factor is personalization. Someone trying to pay down student loans needs something different from a user who wants to automate retirement contributions or track family spending. The best financial wellness apps adapt to different goals and offer relevant recommendations instead of treating every user the same. In practice, that means flexible savings rules, contextual education, debt management tools, spending analysis, and personalized nudges that feel timely rather than intrusive.
Trust also matters more here than in most app categories because these tools often connect directly to bank accounts, credit cards, payroll systems, and investment platforms. If users do not feel confident in the security posture, privacy controls, and reliability of data syncing, they are unlikely to use the product long enough to benefit from it. A useful financial wellness app therefore combines insight, automation, and trust into a single experience that supports better financial behavior over time.
How Financial Wellness Apps Support Employees and Employers
Financial wellness apps are increasingly relevant in workplace programs because financial stress has a direct effect on productivity, morale, and retention. Employees dealing with debt, irregular cash flow, or poor savings habits often carry that stress into work. Platforms that offer budgeting education, earned wage access, loan repayment assistance, and savings tools can reduce that pressure and help employees feel more in control of their financial lives.
For employers, this category is no longer just a nice-to-have benefit. Financial wellness tools can complement a broader employee financial wellness strategy by addressing a major source of stress that traditional healthcare or fitness benefits do not solve on their own. When companies provide relevant financial resources, they can strengthen employee satisfaction and position themselves more competitively in hiring. Tools such as payroll-linked savings, student loan support, and retirement planning resources are especially attractive when organizations want benefits that feel practical and measurable.
The most effective employer-facing solutions do more than offer static educational content. They connect financial guidance with action. That can include helping employees save automatically, access wages responsibly, review debt obligations, or understand how benefits and retirement contributions affect long-term security. In that sense, financial wellness apps function best when they bridge information and behavior, not when they act only as content libraries.
At the same time, business buyers should evaluate these platforms carefully. The right choice depends on workforce needs, payroll integration requirements, reporting expectations, privacy concerns, and whether the company wants a narrowly focused financial benefit or a broader employee wellness platform with financial modules. A good vendor fit depends as much on implementation quality and relevance as it does on the feature list itself.
List of the Best Financial Wellness Apps in 2026
YNAB (You Need a Budget): Budgeting method for employees stuck in the paycheck-to-paycheck cycle. Consumer subscription, with an enterprise program if you want to fund it centrally.
Acorns: Automated micro-investing for first-time investors. Employee-installed, so treat it as a recommendation rather than a benefit you can deploy.
Qapital: Rule-based savings for employees who want to automate a specific goal. Employee-installed, no employer reporting.
Peanut Butter: Employer-purchased student loan repayment, with payroll integration and a repayment dashboard. The clearest fit if your workforce skews graduate and early-career.
Credit Karma: Free credit and spending visibility, ad-supported. Useful as a no-cost recommendation in financial education comms, not as a purchased benefit.
Betterment: Employer-purchased retirement readiness: 401(k) administration, payroll integration, and employee education on a flat annual fee.
PayActiv: Employer-purchased earned wage access. The right answer when the problem is paycheck timing rather than budgeting skill, which is common in hourly and shift workforces.
Oportun Set and Save: Automated savings aimed at people with limited access to traditional banking and credit. Employee-installed, typically free.
Rocket Money: Subscription auditing and bill negotiation, which frees cash without a pay rise. Employee-installed, free tier plus a paid plan.
Albert: Budgeting and savings in one app, with access to human financial advice, which is the part most apps lack. Employee-installed.
Which of These Can an Employer Actually Buy?
This is the question that reorders the whole list, and it is rarely answered in a roundup. Of the ten apps below, three are sold to employers with payroll integration and aggregate reporting, and YNAB adds an enterprise program on top of its consumer plans. The remaining six are consumer products your employees install and pay for themselves. You can promote those in financial education comms, but you cannot buy them centrally, cannot integrate them with payroll, and will never know how many people opened them.
| App | Pressure it solves | Who buys it | Pricing model |
|---|---|---|---|
| PayActiv | Paycheck timing, cash gaps between paydays | Employer | Custom |
| Peanut Butter | Student loan burden | Employer | Annual platform fee plus a per-user monthly rate |
| Betterment at Work | Retirement readiness, 401(k) participation | Employer | Tiered annual plans |
| YNAB | Budgeting habits, paycheck-to-paycheck cycle | Either, enterprise program available | Paid consumer subscription, enterprise custom |
| Credit Karma | Credit score and spending visibility | Employee | Free, ad-supported |
| Rocket Money | Subscription creep, recurring bills | Employee | Free tier plus a paid plan |
| Albert | Scattered money tools, plus human financial advice | Employee | Free tier plus a paid plan |
| Acorns | Starting to invest | Employee | A few dollars per user per month |
| Qapital | Goal-based saving | Employee | A few dollars per user per month |
| Oportun Set and Save | Automated saving with thin banking access | Employee | Typically free |
Read the pricing column carefully, because the two models are not comparable. Per-user-per-month scales with headcount and punishes you for high enrolment, which is the outcome you were trying to buy. A flat annual fee is predictable and rewards adoption. For a workforce of any size, model both against realistic take-up rather than against your total employee count, and remember that the platform-wide options in the Add-Ons section below bundle financial wellbeing with physical and mental health for one fee instead of stacking three vendors.
Detailed Overview - Best Apps for Financial Wellness

YNAB (You Need a Budget)
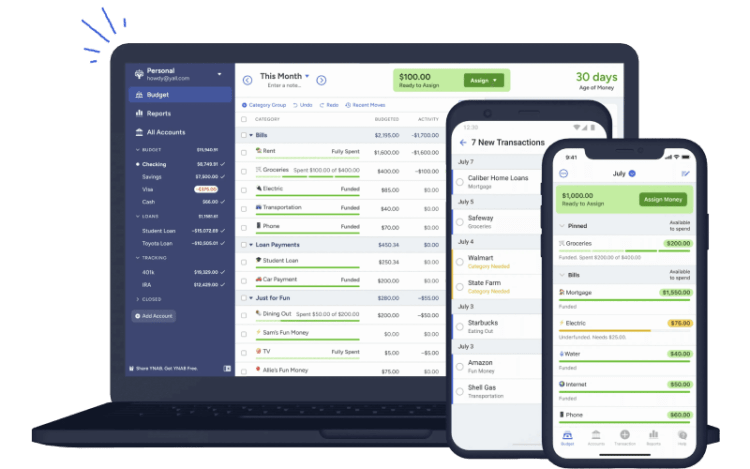
YNAB is a proactive budgeting tool designed to help users gain total control over their money by allocating every dollar a job. The goal of the software is to help users stop living paycheck to paycheck, save money, and get out of debt. It provides tools for tracking expenses, creating a budget, and connecting with other users to stay encouraged and on track.
Recommended for: Entrepreneurs looking to take charge of their finances and establish a strong financial base.
Android App
Yes (Rating: 4.5/5 ⭐️)
iOS App
Yes (Rating: 4.8/5 ⭐️)
Web-Based Portal
Yes
Goal Tracking
Comprehensive Budgeting Education
Integrated Loan Planner
Four Rules
Envelope Method
Self-Service Plans
Monthly or annual subscription
Enterprise Program
Custom Pricing

Acorns
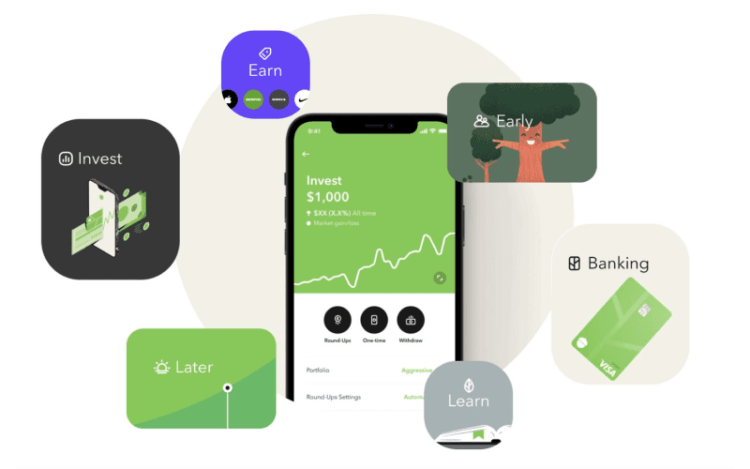
Acorns is a good fit for people who want to start investing but do not know where to begin or find it difficult to keep up with the stock market. As a pioneer in micro-investing, Acorns simplified a complex category and made investing more accessible. While the app comes with a cost, it can be worthwhile for users who want to build a stock portfolio but have limited time.
Recommended for: Beginner investors, young professionals, or parents looking to start investing for their children.
Android App
Yes (Rating: 4.4/5 ⭐️)
iOS App
Yes (Rating: 4.7/5 ⭐️)
Web-Based Portal
Yes
Automated Roundups
Diversified Portfolios
Retirement Accounts (Acorns Later)
Found Money Rewards Program
Family Account Options
Tiered Plans
A few dollars per user per month

Qapital
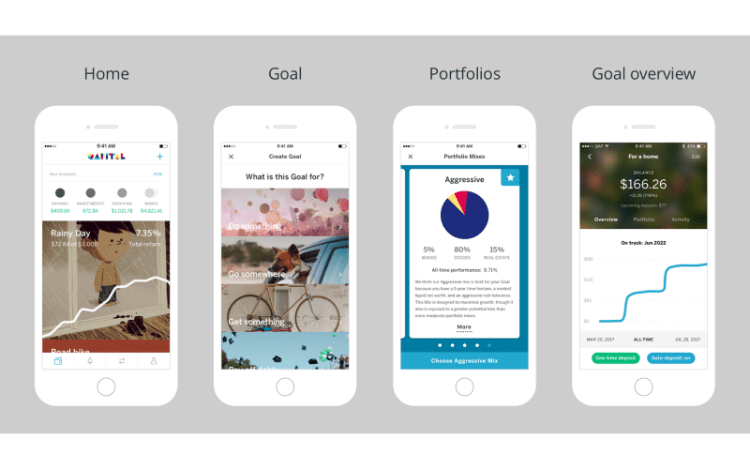
Qapital is a personal finance app designed to help users save and budget with customizable savings goals, automated rules, and spending tracking. It offers flexibility and user control and focuses on making saving money feel more engaging. Its goal-oriented approach makes it a strong option for people who prefer a hands-on way to manage finances.
Recommended for: Individuals who want more control over their savings rules and are interested in a more interactive approach to managing finances.
Android App
Yes (Rating 4.5/5 ⭐)
iOS App
Yes (Rating 4.8/5 ⭐️)
Web-Based Portal
Yes
Customizable Savings Goals
Budgeting Tools
No-Overdraft Protection
Rule-based Transfers
Investing
Lending
Tiered Plans
A few dollars per user per month

Peanut Butter
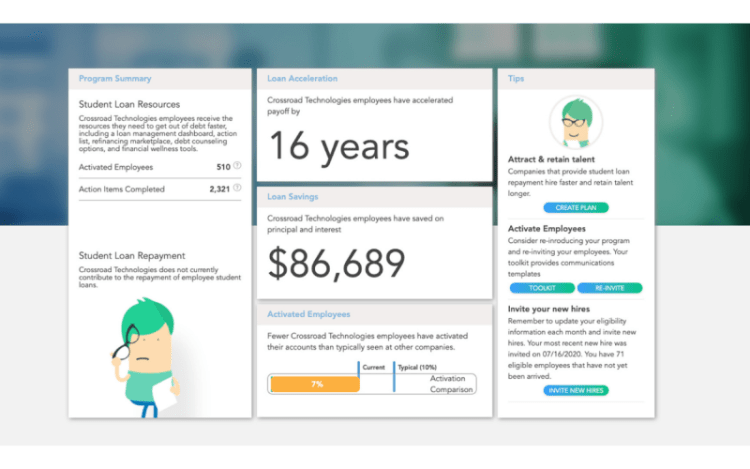
Peanut Butter provides student loan repayment benefits, helping companies attract and retain talent by addressing a major employee concern: student debt. With Peanut Butter’s financial wellness tools, companies can shorten hiring times, improve tenure, boost engagement, and help employees pay off debt faster.
Recommended for: Mid-sized to large companies looking to enhance their benefits packages and support employee financial wellness.
Android App
Yes (Rating: 4.6/5 ⭐️)
iOS App
Yes (Rating: 4.7/5 ⭐️)
Web-Based Portal
Yes
Financial Counseling
Access Directory
Seamless Payroll Integration
Employee Dashboard for Tracking Repayments
Tax-Advantaged Benefits
Federal & Private Loans Support
Salesforce
Carvana
Allstate
Repayment
Annual fee plus a per-user monthly rate
Resources
Annual fee
Refinancing
For Free

Credit Karma
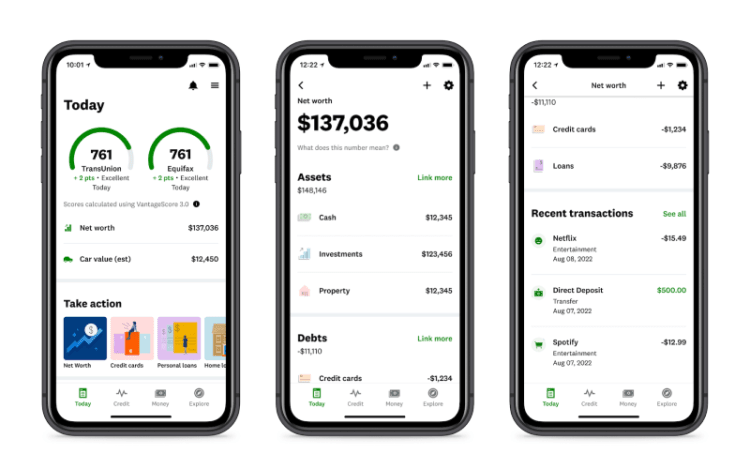
Credit Karma, owned by Intuit, helps users access credit scores from TransUnion and Equifax and review detailed credit reports to track changes and identify potential errors. It also offers recommendations for credit cards, loans, insurance products, and savings accounts.
After Mint shut down in March 2025, Credit Karma absorbed several Mint-style features such as net worth tracking, spending analysis, and cash flow monitoring. The platform now uses AI and data analysis to provide more tailored financial insights and product recommendations.
Recommended for: Individuals or small businesses seeking a single view of their finances.
Android App
Yes (Rating: 4.7/5 ⭐️)
iOS App
Yes (Rating: 4.8/5 ⭐)
Web-Based Portal
Yes
Budget Tracking
Bill Reminders
Real-time Sync across Multiple Accounts
Credit Score Monitoring
Free to Use
Supported by Ads

Betterment
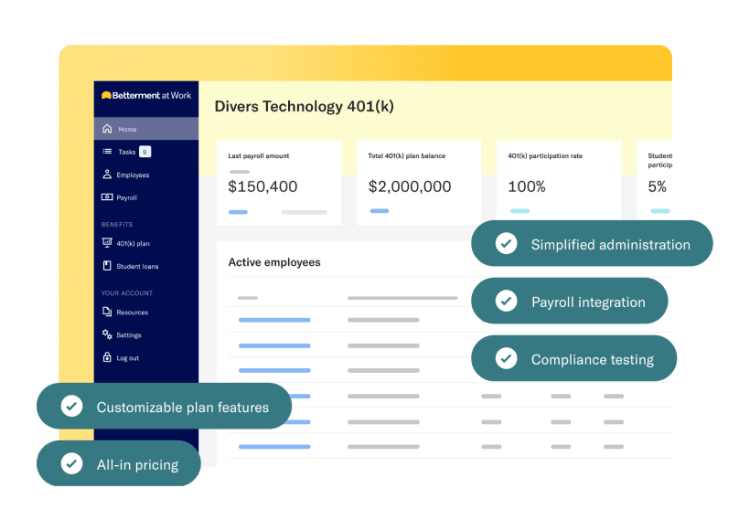
Betterment is a financial wellness app that offers automated investment management through a robo-advisor model. It provides personalized portfolio allocation based on financial goals such as buying a home or planning for retirement, then maps those goals to tailored investment strategies.
Betterment at Work extends that model into the employer space with personalized 401(k) plans and investment advice designed to improve employee financial wellness.
Recommended for: Medium to large companies aiming to enhance employee financial wellness through personalized retirement plans.
Android App
Yes (Rating: 4.5/5 ⭐️)
iOS App
Yes (Rating: 4.7/5 ⭐️)
Web-Based Portal
Yes
Personalized Retirement Planning
Automatic Portfolio Rebalancing
Employee Financial Education
Socially Responsible Investment Options
Tax-Loss Harvesting
Seamless Payroll Integration
Tiered Annual Plans
Essential, Pro, and Flagship, quoted annually

PayActiv
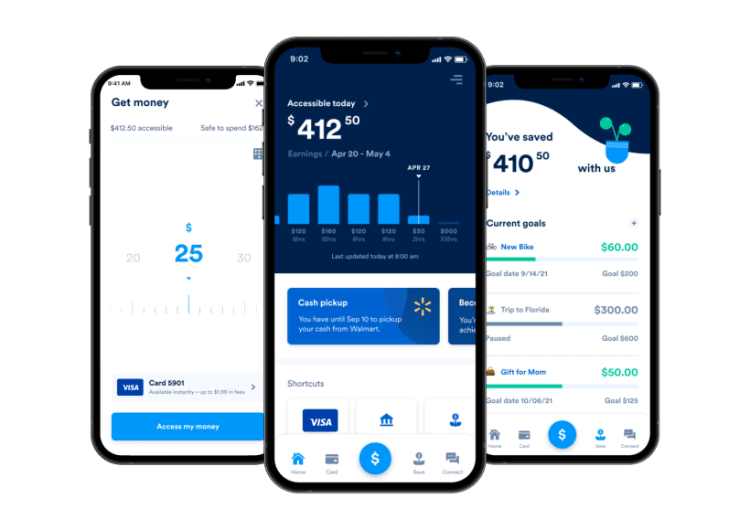
PayActiv is a financial wellness platform that offers employees access to earned wages before payday alongside tools that improve financial health. It is designed to reduce financial stress by giving employees earlier access to earned income and helping them avoid payday loans and overdraft fees.
Recommended for: Businesses looking to improve employee satisfaction and retention by offering financial wellness benefits.
Android App
Yes (Rating: 4.5/5 ⭐️)
iOS App
Yes (Rating: 4.7/5 ⭐️)
Web-Based Portal
Yes
Financial Counseling
Discounts & Benefits
Savings and Budgeting Tools
Bill Payment Services
Earned Wage Access (EWA)
Uber
Walmart
Subway
Custom Pricing
Contact PayActiv

Oportun Set and Save (Digit)
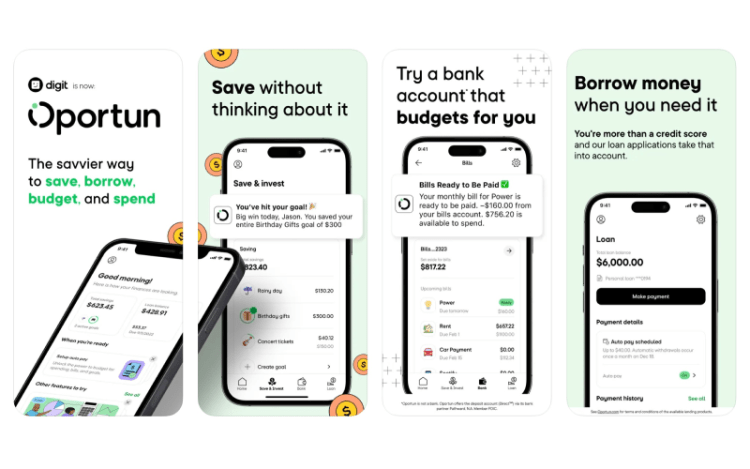
Oportun Set and Save uses automation and AI to analyze income and spending patterns, then transfers funds from a linked checking account to savings when it determines the user can afford it. It is not just a round-up tool. Users set objectives such as saving for tickets or paying down debt, while the app handles much of the budgeting logic.
Your FDIC-insured Oportun account can also receive a quarterly savings incentive when you save for three consecutive months, and the company can help members avoid overdrafts by covering eligible autosave-related overdraft fees within monthly limits.
Recommended for: Individuals looking to build savings automatically, especially those who may have limited access to traditional banking and credit services.
Android App
Yes (Rating: 4.5/5 ⭐️)
iOS App
Yes (Rating: 4.6/5 ⭐️)
Web-Based Portal
Yes
Automated Savings
Access to Credit
Flexible Contributions
Savings, Budgeting, and Investing Tools
Typically Free
With Options for Accessing Loans

Rocket Money
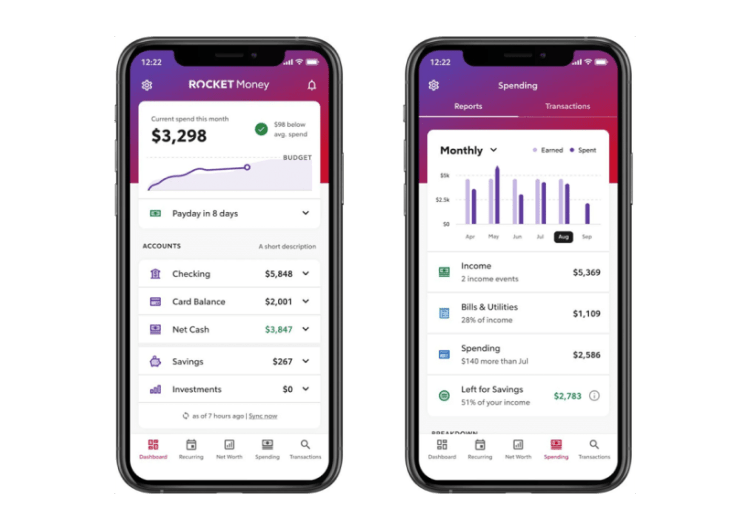
Rocket Money, formerly Truebill, is a financial management app designed to help users track subscriptions, manage bills, and optimize spending. It provides a dashboard that shows recurring payments, identifies subscriptions, and helps users cancel services they no longer use.
It also includes bill negotiation, budgeting tools, net worth tracking, and automated savings features, making it useful for people who want more visibility and control over everyday finances.
Recommended for: Individuals who want to manage their finances more effectively, especially those with multiple subscriptions or recurring expenses.
Android App
Yes (Rating: 4.3/5 ⭐️)
iOS App
Yes (Rating: 4.5/5 ⭐️)
Web-Based Portal
Yes
Subscription Tracking
Bill Negotiations
Spending Insights
Budgeting Tools
Automated Savings
Net Worth and Credit Score
Basic
Free
Premium
Paid plan

Albert
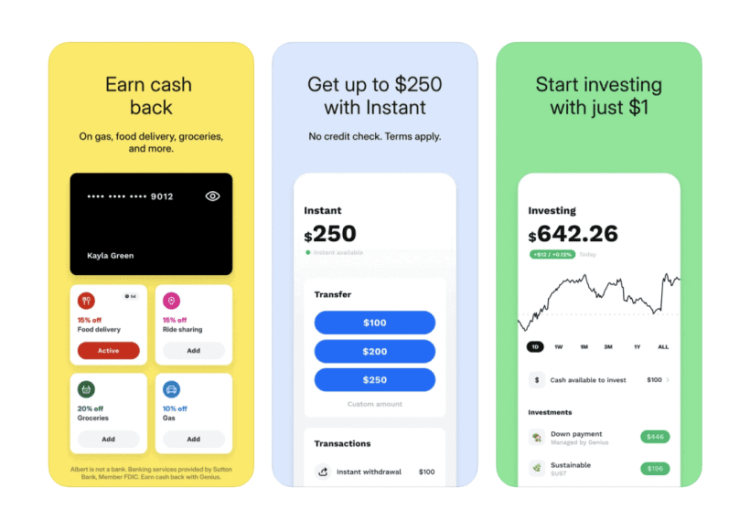
Albert is a personal finance app that combines budgeting tools, savings automation, and access to financial advice in one platform. Users can earn cash-back rewards with an Albert Cash Account and debit card across several spending categories, and they may also view paychecks up to two days earlier.
Albert Budgeting organizes spending and negotiates vendor prices to help reduce costs. Users can begin investing with as little as $1, and the platform does not require minimum balances, overdraft fees, or maintenance fees for basic use.
Recommended for: Individuals who want a comprehensive financial tool that covers everything from budgeting to investing, with access to personalized financial advice.
Android App
Yes (Rating: 4.1/5 ⭐️)
iOS App
Yes (Rating: 4.6/5 ⭐️)
Web-Based Portal
Yes
Smart Savings
Genius Financial Advice
Budget Tracking
Cash Advances
Investing Options
Basic
Free
Genius
Paid subscription
Add-Ons
Below are some of the comprehensive employee wellness apps that did not make the main list because they do not directly fall under the category of financial wellness. However, they offer services through their platforms that encourage the financial well-being of employees and are worth considering.

Vantage Fit
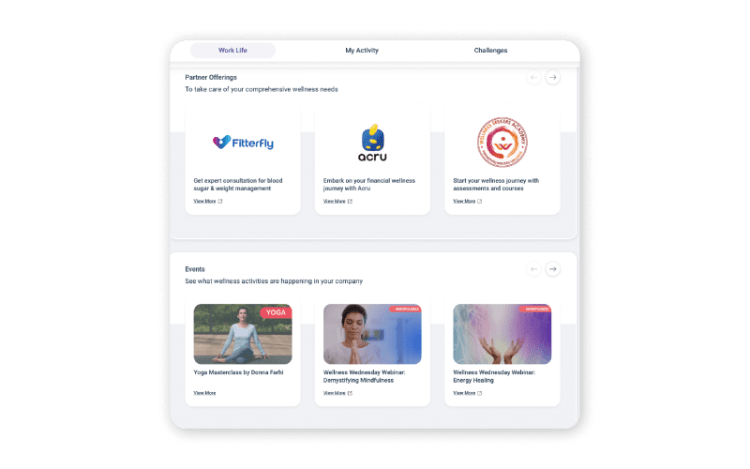
Vantage Fit is a corporate wellness platform that addresses physical, mental, financial, and social well-being. For financial health, it offers solutions to educate employees about healthy money habits and reduce financial stress. The platform also includes a marketplace that connects employees with partners offering services for savings, investments, loans, and financial planning.
Recommended for: Companies seeking to enhance overall employee well-being focusing on financial health and comprehensive wellness solutions.
Android App
Yes (Rating: 4.5/5 ⭐️)
iOS App
Yes (Rating: 4.8/5 ⭐️)
Web-Based Portal
Yes
Single Challenge (4 weeks)
Basic from $250 at 25 employees, rising to $4,000 at 1,000
Unlimited (annual)
Basic from $500 at 25 employees, rising to $8,000 at 1,000
Pro tier
25% above Basic at any headcount
Above 1,000 employees
Custom pricing

Optum
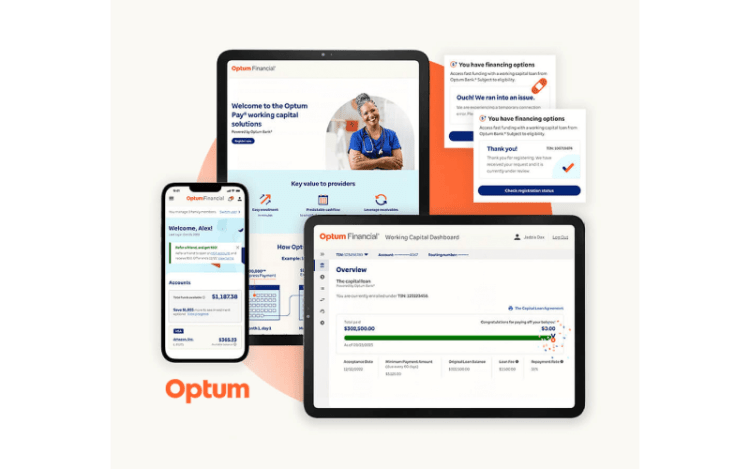
Optum includes financial wellness as part of its broader well-being offerings. This includes financial literacy tools, support for managing healthcare costs, and resources for reducing financial stress. The platform is designed around the idea that financial strain influences broader health outcomes.
Recommended for: Organizations seeking to integrate financial wellness with overall health initiatives to improve employee well-being.
Android App
Yes (Rating: 4.1/5 ⭐️)
iOS App
Yes (Rating: 4.6/5 ⭐️)
Web-Based Portal
Yes
Custom Pricing
Price on Request

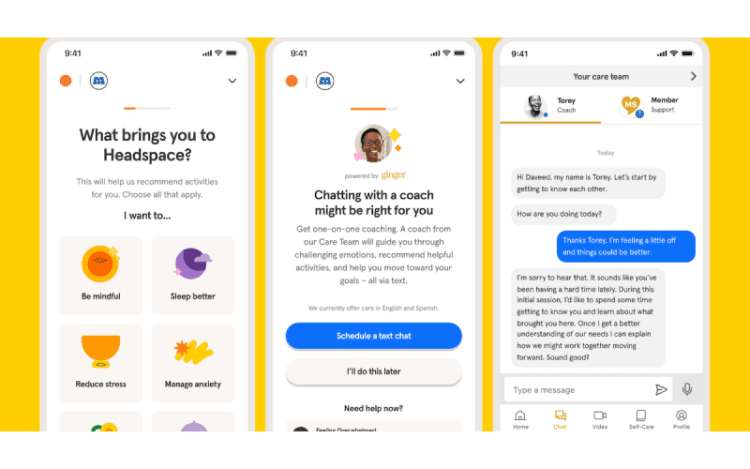
Headspace for Work
While Headspace for Work primarily focuses on mental health, it includes content related to managing financial stress. It addresses financial anxiety through mindfulness exercises and guided meditations intended to support a healthier mindset toward money and day-to-day stressors.
Recommended for: Organizations seeking to integrate mental health support with tools to manage financial stress and promote overall well-being.
Android App
Yes (Rating: 4.6/5 ⭐️)
iOS App
Yes (Rating: 4.9/5 ⭐️)
Web-Based Portal
Yes
Custom Pricing
Price on Request
How Do You Roll Out a Financial Wellness App So Employees Actually Use It?
Adoption, not procurement, is where most of these programs fail. The encouraging part is that access converts when the offer is visible: PwC found 83% of Gen Z and 79% of millennial employees whose employers offered financial wellness services went on to use them to control spending, pay down debt, and build savings. The tool is rarely the constraint. The rollout is.
Name the pressure before you shortlist. An engagement survey or a benefits utilization review will usually show whether your workforce is dealing with paycheck timing, debt load, or long-term savings, and those three point at completely different vendors. Buying a budgeting app for a workforce that is short of cash between paydays solves nothing, however good the app is. Setting clear financial wellness goals first keeps the shortlist honest.
Then pilot narrowly. One department, thirty to sixty days, and a single success measure: weekly active users. Enrolment counts flatter everyone and tell you nothing, because a payroll-linked signup is not the same as a habit. Price the pilot into your wellness program budget before you negotiate the annual contract, since per-employee-per-month pricing across this category spans free to several dollars, and the employer-sold options run from an annual platform fee in the high hundreds to several thousand a year.
Finally, be explicit about privacy, because it decides whether anyone connects an account. These tools link to bank accounts, cards, and payroll, and employees will not do that with a product they believe their employer can read. Insist on aggregate-only reporting, say so in the launch communication rather than burying it in a policy document, and make participation genuinely voluntary. A financial wellness app that no one trusts is a line item, not a benefit.
Benefits of Using Financial Wellness Apps
Financial wellness apps offer several benefits that contribute to better financial management and overall well-being. Some of the key benefits include:
Convenience and Accessibility: Financial wellness apps offer the convenience of quickly accessing your financial status anytime, anywhere, with just a few taps on your smartphone or clicks on your computer.
Personalized Insights and Recommendations: Many personal finance apps use advanced algorithms and machine learning to offer tailored insights and recommendations. They help users reach financial goals by identifying areas for improvement, such as reducing unnecessary spending or increasing savings.
Automated Budgeting and Tracking: Manual budgeting and expense tracking can be laborious and error-prone. Financial wellness apps automate these tasks by connecting to accounts, categorizing transactions, and offering real-time spending and budget information.
Goal-Setting and Progress Tracking: Financial wellness apps allow users to set goals, such as building an emergency fund, and monitor progress over time.
Financial Literacy and Educational Materials: Many financial wellness apps include articles, videos, and interactive courses that improve financial literacy, support healthier financial habits, and simplify complex money topics.
Financial wellness apps enhance convenience, personalization, and automation while supporting goal-setting and financial literacy, making them valuable tools for managing personal finances effectively.
Potential Challenges of Using Financial Wellness Apps
While financial wellness apps offer numerous benefits, they also come with potential challenges. Here are some key concerns to consider:
Data Security and Privacy Concerns: Data security and privacy are major concerns with financial wellness apps. Linking bank accounts raises questions about how sensitive financial data could be misused or compromised. Strong encryption and privacy standards matter.
Limited Capabilities for Tricky Financial Circumstances: Financial wellness apps may have limitations when handling complex financial situations such as estate planning, tax optimization, or managing multiple investment portfolios. Specialized advice may still require professional assistance.
Problems with Integration Across Several Accounts/Institutions: Integrating financial information from multiple accounts or institutions into one app can be difficult. This may lead to issues with data accuracy or completeness and reduce the quality of insights and recommendations.
Understanding these potential challenges can help users make informed decisions about which financial wellness apps best meet their needs and how to use them effectively.
FAQs
Q. How can Financial Wellness Apps help me reduce debt?
A: Many financial wellness apps offer debt payoff tools such as automated savings plans, debt repayment strategies, and personalized budgeting advice. Apps like YNAB and Albert can help users build structured plans for paying off credit card debt, student loans, and other liabilities.
Q. Are Financial Wellness Apps safe to use?
A: Yes, most reputable financial wellness apps use bank-level security measures, including encryption, multi-factor authentication, and fraud detection. Apps such as Credit Karma and Chime are widely used and follow strict data privacy standards.
Q. Can Financial Wellness Apps improve my credit score?
A: Yes, many financial wellness apps can help improve credit scores by offering tools to monitor credit, manage debt, and stay on top of payments. Credit Karma and Chime are useful for credit tracking and personalized credit improvement suggestions.
Q. Are there any free Financial Wellness Apps?
A: Yes, several financial wellness apps offer free versions with essential features. Credit Karma is a popular example that offers budgeting, credit score tracking, and financial insights at no cost, while some premium features may require payment.
Q. What Financial Wellness Apps are best for employees?
A: Apps like Betterment at Work, Peanut Butter, and Brightside offer employee-specific financial wellness tools. These platforms provide 401(k) management, student loan repayment assistance, and financial coaching, making them relevant for businesses that want to support workforce financial health.
Q. Can employers buy financial wellness apps directly?
A: Only some of them. PayActiv, Peanut Butter, and Betterment at Work are sold to employers, integrate with payroll, and report usage back in aggregate. YNAB offers an enterprise program alongside its consumer plans. Acorns, Qapital, Credit Karma, Rocket Money, Albert, and Oportun Set and Save are consumer products your employees install and pay for themselves, so you can recommend them but you cannot deploy or measure them.
Q. Can my employer see my bank account through a financial wellness app?
A: In a properly configured employer-purchased program, no. The employer dashboard should report only aggregate figures such as enrolment and active users, never individual balances, transactions, or debts. Because this is the single biggest barrier to employees connecting an account, ask the vendor to state in writing exactly what the employer can see, and say so plainly when the program is announced.
Q. How do you measure ROI on a financial wellness app?
A: Start with weekly active users rather than enrolment, because a payroll-linked signup is not the same as a habit. Once usage holds, look at the outcomes the tool is meant to move, such as retirement contribution rates, take-up of earned wage access instead of high-cost credit, or retention in the groups under most pressure. Bank of America found 9 in 10 employers who offer a financial wellness program report a measurable return in satisfaction, productivity, and retention.